For much of the past decade, automotive strategy was built around a relatively straightforward assumption: electrification would progress steadily, battery-electric vehicles would take an increasing share of the global market, and suppliers needed to reposition their portfolios accordingly.
That transition is still underway. But the path is proving far less uniform than many strategic plans assumed.
The most important development is not that electrification has stopped. It is that the transition has become increasingly regional.
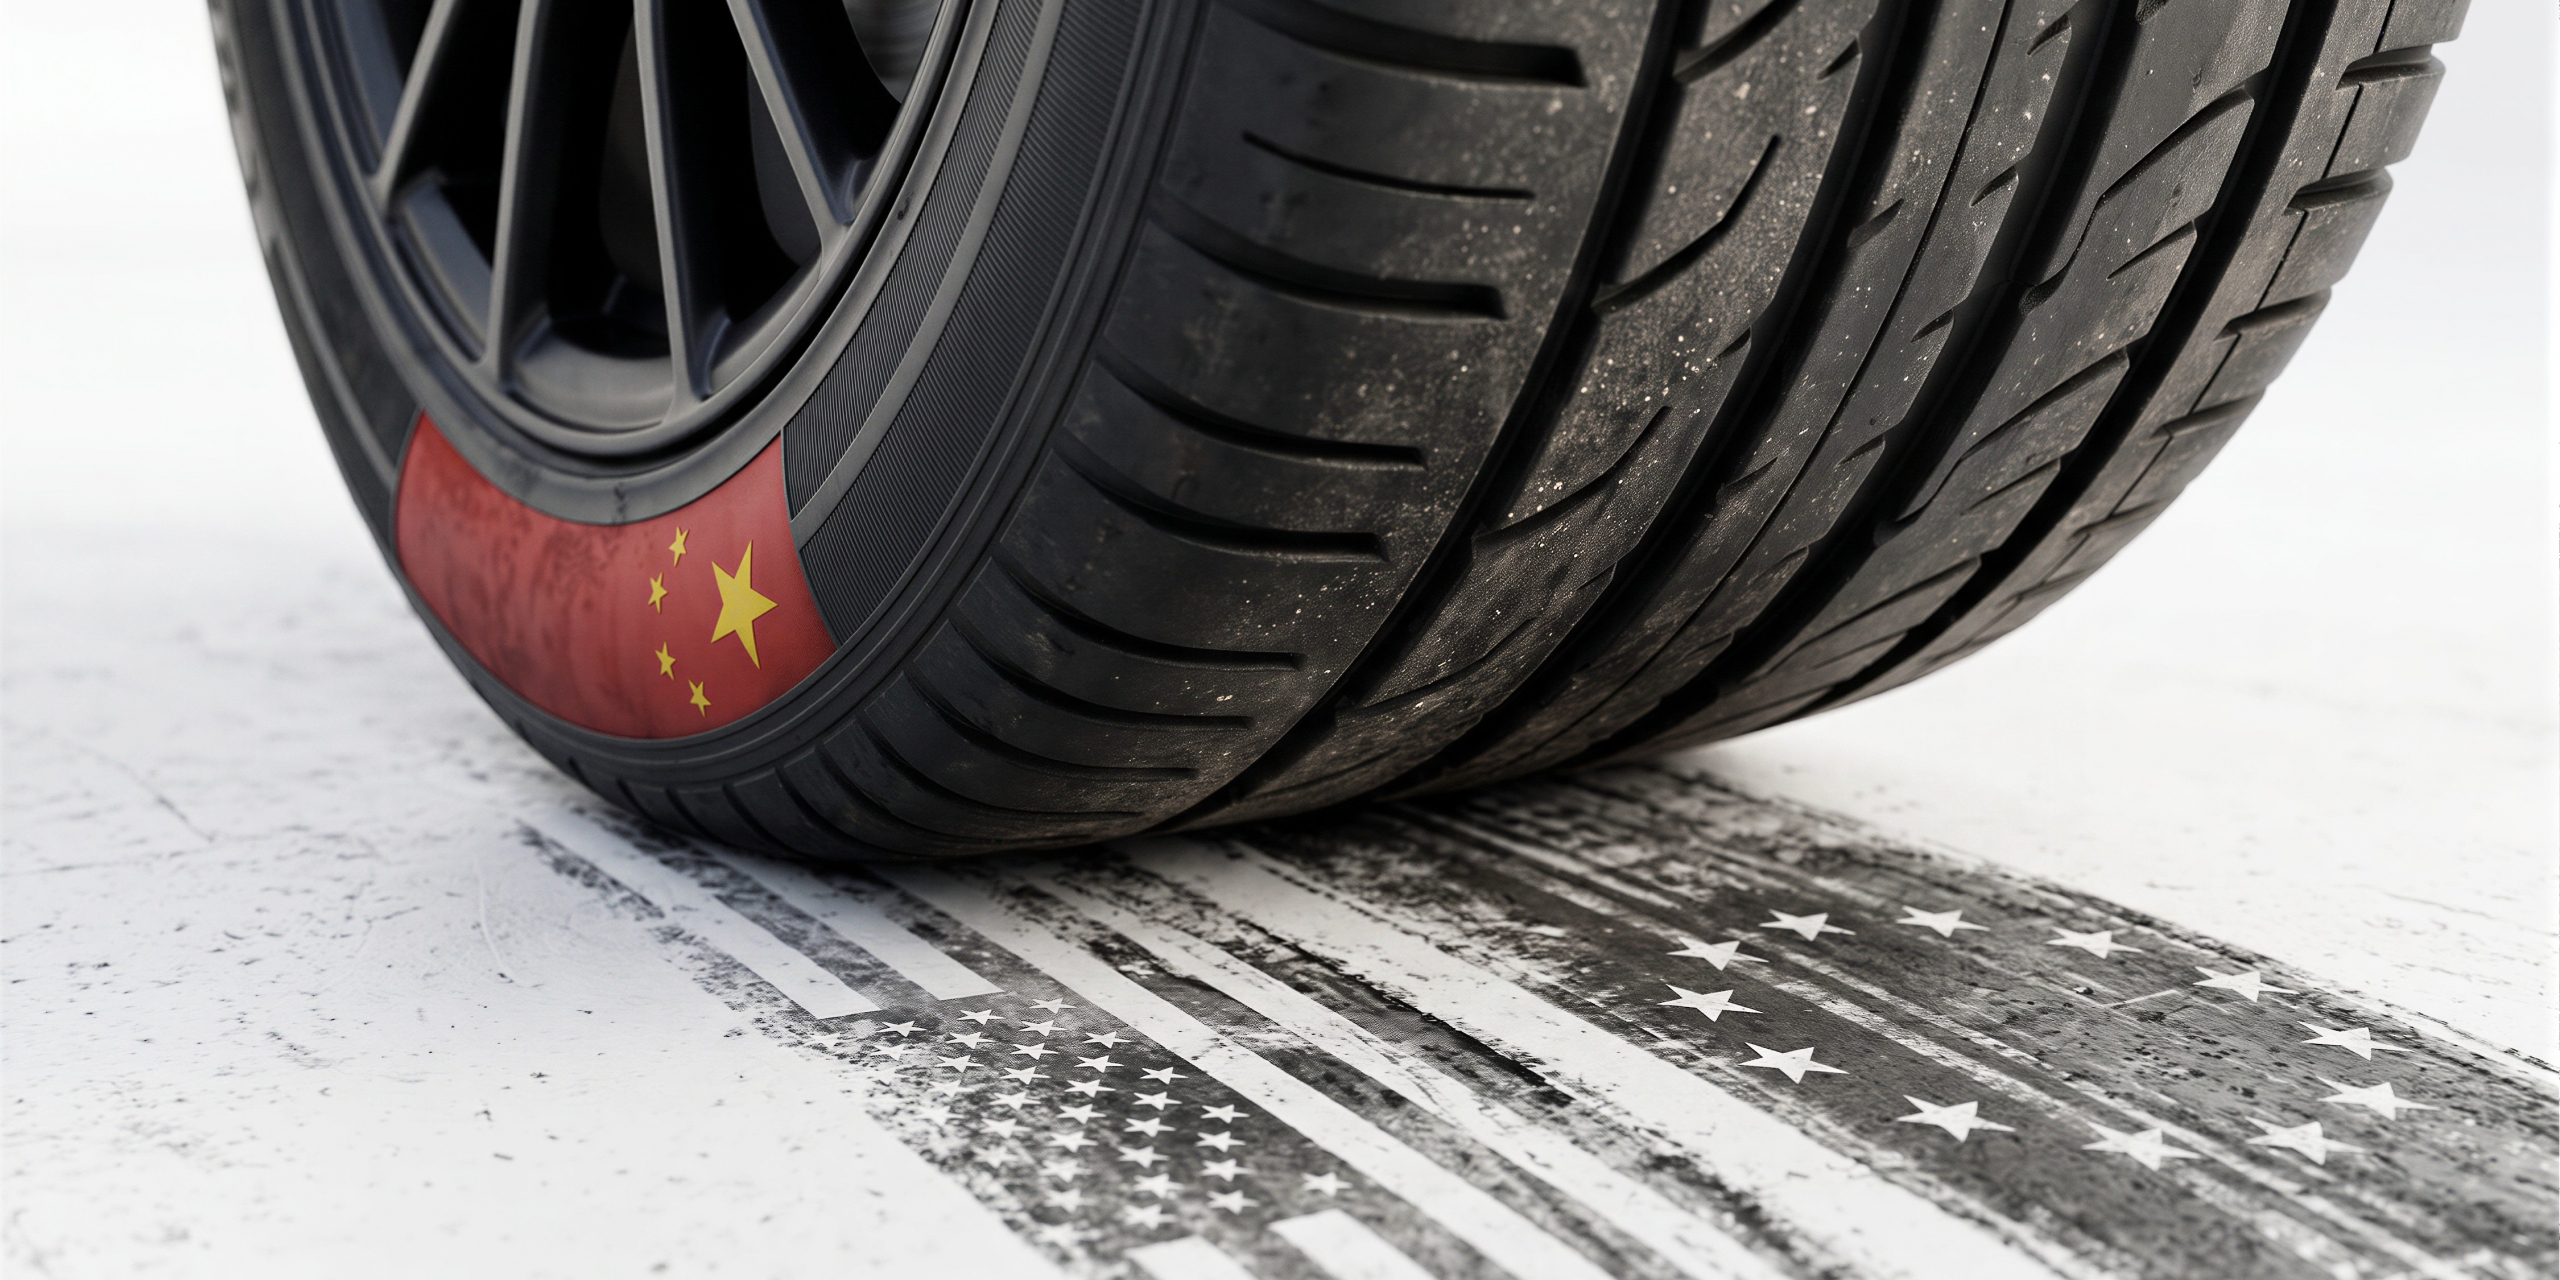
Current industry forecasts suggest battery-electric vehicles could approach 60% of the Chinese market over the next five years and nearly 40% in Europe. North America looks very different. BEVs may represent only about 10% of the market over the same period, while full hybrids and plug-in hybrids together could approach one-third of vehicle sales.
For Tier 1 suppliers, the implications are significant.
There is no longer a single global powertrain transition around which to build a portfolio. The technology mix required to succeed in China may look very different from the portfolio required in North America, while Europe presents another set of requirements entirely.
The strategic challenge is therefore no longer simply how fast to electrify. It is how to allocate capital across increasingly divergent markets while maintaining attractive returns.
Growth Is Not the Same as Strategic Attractiveness
One of the most consequential mistakes made during the first phase of electrification was confusing market growth with a right to win.
Traditional powertrain suppliers understandably saw the expected growth of EVs and moved aggressively into electric drives, motors, inverters, battery technologies, and other electrification components. In many cases, the logic was compelling: if traditional ICE businesses ultimately declined, suppliers needed new growth platforms.
The issue was not the decision to invest in electrification. It was that some suppliers entered attractive markets without first answering a more fundamental question:
Why should we win?
Rapidly growing markets attract competitors and capital. Electric-vehicle technologies demonstrate this particularly well.
Chinese suppliers have built enormous scale across batteries, electric-drive systems, power electronics, and many associated technologies. That scale has been reinforced by a domestic market that adopted electrification faster than Western markets, allowing Chinese companies to move aggressively down manufacturing cost curves, accelerate development cycles, and deepen customer relationships.
The result is that many electrification categories have become intensely competitive precisely because they are growing.
For a Western Tier 1 considering additional investment today, participation in a growing market is no longer sufficient justification. Management should be able to demonstrate a credible advantage based on proprietary technology, competitive cost, achievable scale, customer access, system capability, or manufacturing know-how.
Without that advantage, growth can consume capital without creating acceptable returns.
China Changes the Investment Equation
This is particularly important when assessing China.
For years, China was viewed almost automatically as a strategic growth market for Western suppliers. That assumption deserves to be reconsidered.
China remains an enormous automotive market, but the competitive structure has changed significantly. Local OEMs and suppliers increasingly possess advantages in scale, cost, development speed, and electrification capability. For many Western Tier 1s, the hurdle for incremental China investment should therefore be materially higher.
The question for a board should no longer be:
How much should we invest in China?
It should be:
Where in China do we genuinely have a right to win—and where should we decline to deploy additional capital?
There will still be opportunities where proprietary technology, an existing global customer relationship, or a differentiated capability creates an attractive investment case.
But China should not receive capital simply because it is large, fast-growing, or strategically important.
The burden of proof has changed.
Product Cadence Is Becoming a Competitive Weapon
Portfolio strategy must also consider which OEMs are positioned to win.
Historically, Tier 1 account strategies have often been anchored in current customer size: which OEM has the greatest volume, which account generates the most revenue, and where today’s largest platforms sit.
That remains relevant, but it is increasingly incomplete.
In North America and Europe, some vehicle programs are being delayed and product cycles extended as OEMs become more selective about capital. Meanwhile, many Chinese domestic manufacturers have developed a different operating model built around faster development, more frequent model introductions, and greater customer-facing product variety.
Their competitive advantage is not simply that they build EVs.
They are also creating fresher product portfolios faster.
That allows them to incorporate new technologies more quickly, respond to changing consumer expectations, and maintain product relevance at a pace many traditional manufacturers struggle to match.
For suppliers, this creates an important strategic principle:
Yesterday’s OEM market share tells you where the revenue is. Product cadence may tell you where the revenue is going.
A large OEM with an aging portfolio, repeated program extensions, and declining product investment may represent a less attractive five-year growth opportunity than a smaller manufacturer actively refreshing its lineup and gaining momentum.
Tier 1 suppliers should therefore place greater emphasis on product cadence, platform timing, and customer investment when allocating commercial and engineering resources.
Suppliers Must Match the Speed of Winning Customers
There is a second implication.
It is not enough to identify faster-moving OEMs. Suppliers must also be capable of operating at their speed.
A Tier 1 built around long development cycles, extensive one-off engineering, and large program-specific capital commitments will find it increasingly difficult to earn attractive returns as customer product cycles compress.
The supplier operating model must evolve as well.
That means greater component reuse, more modular product architectures, standardized interfaces, faster validation, and lower incremental engineering requirements. The objective is to create more customer-facing variation without recreating the underlying technology for every program.
The goal is straightforward:
More launches, faster, with less incremental capital.
Speed by itself is not the advantage. Speed combined with reuse, standardization, and capital efficiency is.
The Strategic Response: A Portfolio and Capital Reset
The implication for Tier 1 CEOs and boards is larger than simply updating the EV forecast.
Many suppliers need a portfolio and capital reset.
Every business should be challenged against four questions.
Where do we genuinely have a right to win?
Growing markets deserve capital only when the supplier has a defensible competitive advantage and a credible path to returns.
Which businesses should we grow, harvest, or exit?
Mature ICE-related businesses should not automatically be abandoned. Many can continue generating attractive cash for years. The objective should be to minimize incremental capital, maximize cash generation, and redeploy those proceeds toward higher-return, more resilient opportunities. Exit should be reserved for businesses that are subscale, undifferentiated, or structurally incapable of generating acceptable returns.
Are we allocating resources toward the OEMs most likely to win?
Customer strategy should increasingly incorporate product freshness, development cadence, and future market momentum rather than relying primarily on today’s revenue base.
Can our operating model earn attractive returns at higher speed?
Shorter customer cycles require greater reuse, more modularity, and less engineering and capital per incremental program.
Across all four questions, management should apply a regional lens. China, Europe, and North America are no longer following the same propulsion pathway, and capital allocation should reflect those differences.
The hierarchy should remain clear:
Returns first. Resilience second. Growth third.
Growth still matters. But growth without differentiation, capital efficiency, and a clear right to win is not necessarily value creation.
The first phase of electrification rewarded ambition.
The next phase will reward discipline.